
Lithium: A Critical Mineral for the Energy Transition
Market Opportunity
Lithium mining and lithium exploration are key drivers of the global clean energy transition. Lithium is on the Critical Minerals List in the U.S., Canada, the E.U., and multiple other countries.
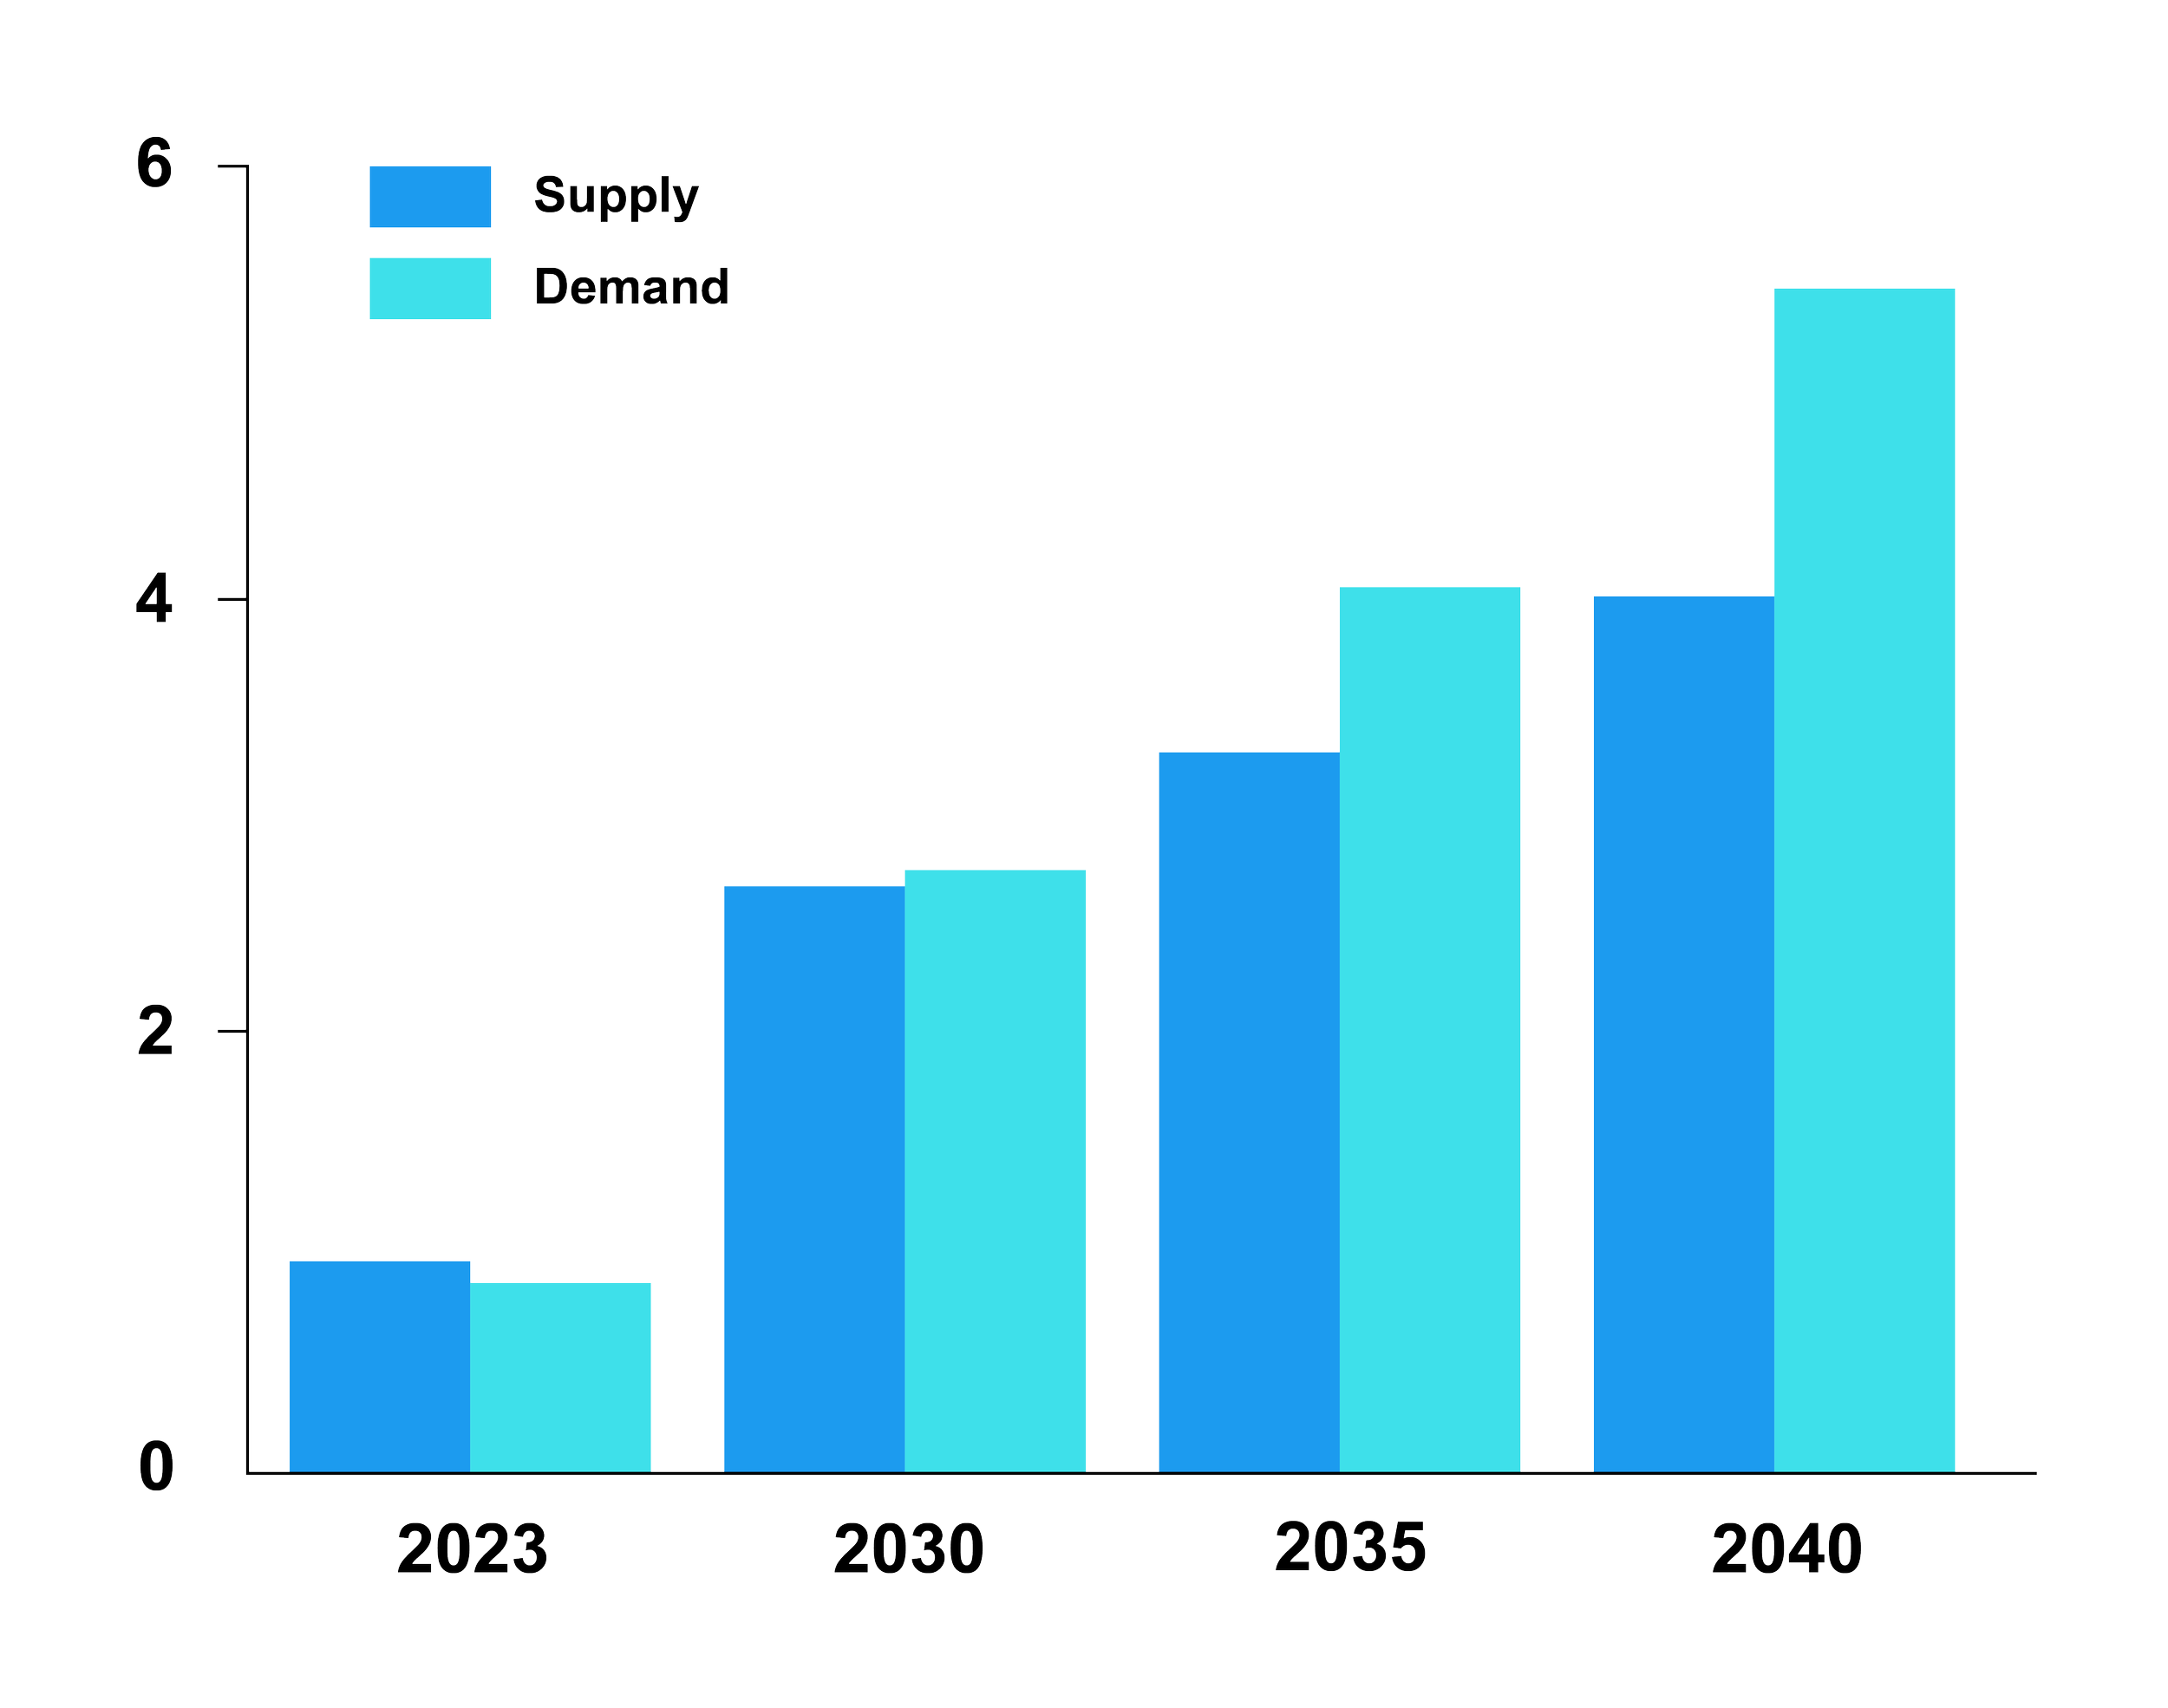
As governments implement decarbonization policies and automakers commit to phasing out internal combustion engines, global lithium demand is expected to outpace supply well into the next decade.
This supply-demand imbalance presents a compelling opportunity for lithium miners, particularly those positioned in politically stable regions with supportive regulatory frameworks.
Lithium supply deficit to emerge by late 2020s:
Lithium’s Primary Uses
Rechargeable batteries for electric vehicles (EVs)
BESS (Battery Energy Storage System) for electricity storage including data centres
Electronics
It also has applications in Pharmaceuticals, Glass, Ceramics and Aerospace.
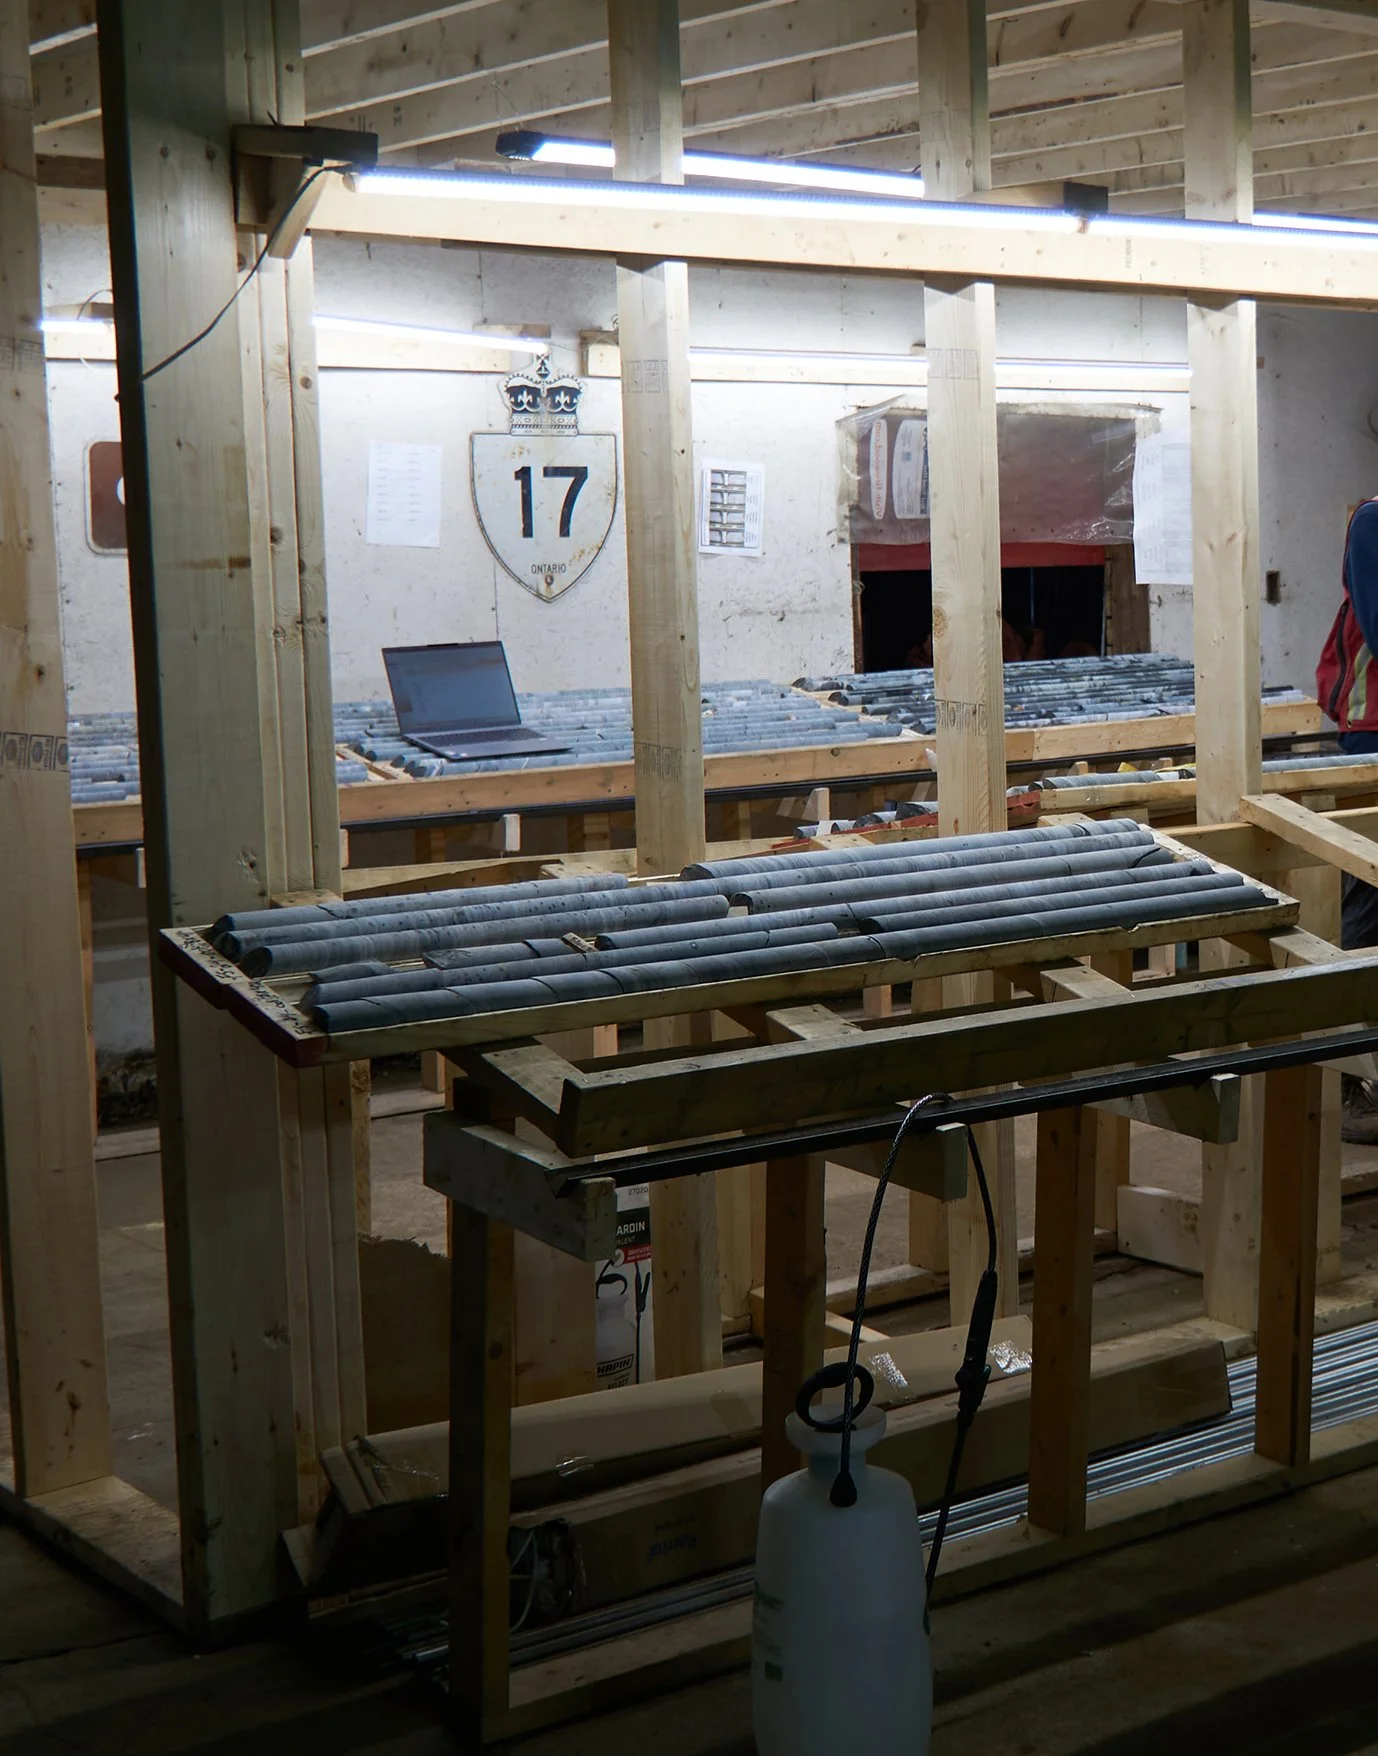
Lithium is produced from either hard rock pegmatite (spodumene or lepidolite or petalite) or from salar brines (salt lakes).
The two processes for extraction are drastically different, with one being the traditional mining and ore processing with rare metals credits, while the other is more concentrated through solar evaporation ponds, followed by other processes such as membrane technology or solvent extraction. There have also been discoveries of lithium in clay hectorite.
The market price of 99.5% lithium carbonate, the most widely traded price benchmark, was around US$ 20,000 per metric tonne in early September 2026. This price has been extremely volatile, having been at US$ 10,000 in 2020, then briefly peaking at US$ 80,000 at the end of 2022, down to US$8,300 in mid 2025 and now back up to the current level.
As demand for electric vehicles, data centres and battery technologies grows, companies involved upstream in lithium mining are gaining attention, and lithium shares are becoming an increasingly attractive option for forward-looking investors.
Explore our metals